The exclusions that apply no matter who the work is for
The exclusions are short and specific, and they do not bend to purpose. CRA lists them on its line 31285 page, which also tells claimants to keep supporting documents in case they are requested and not to send them with the return.
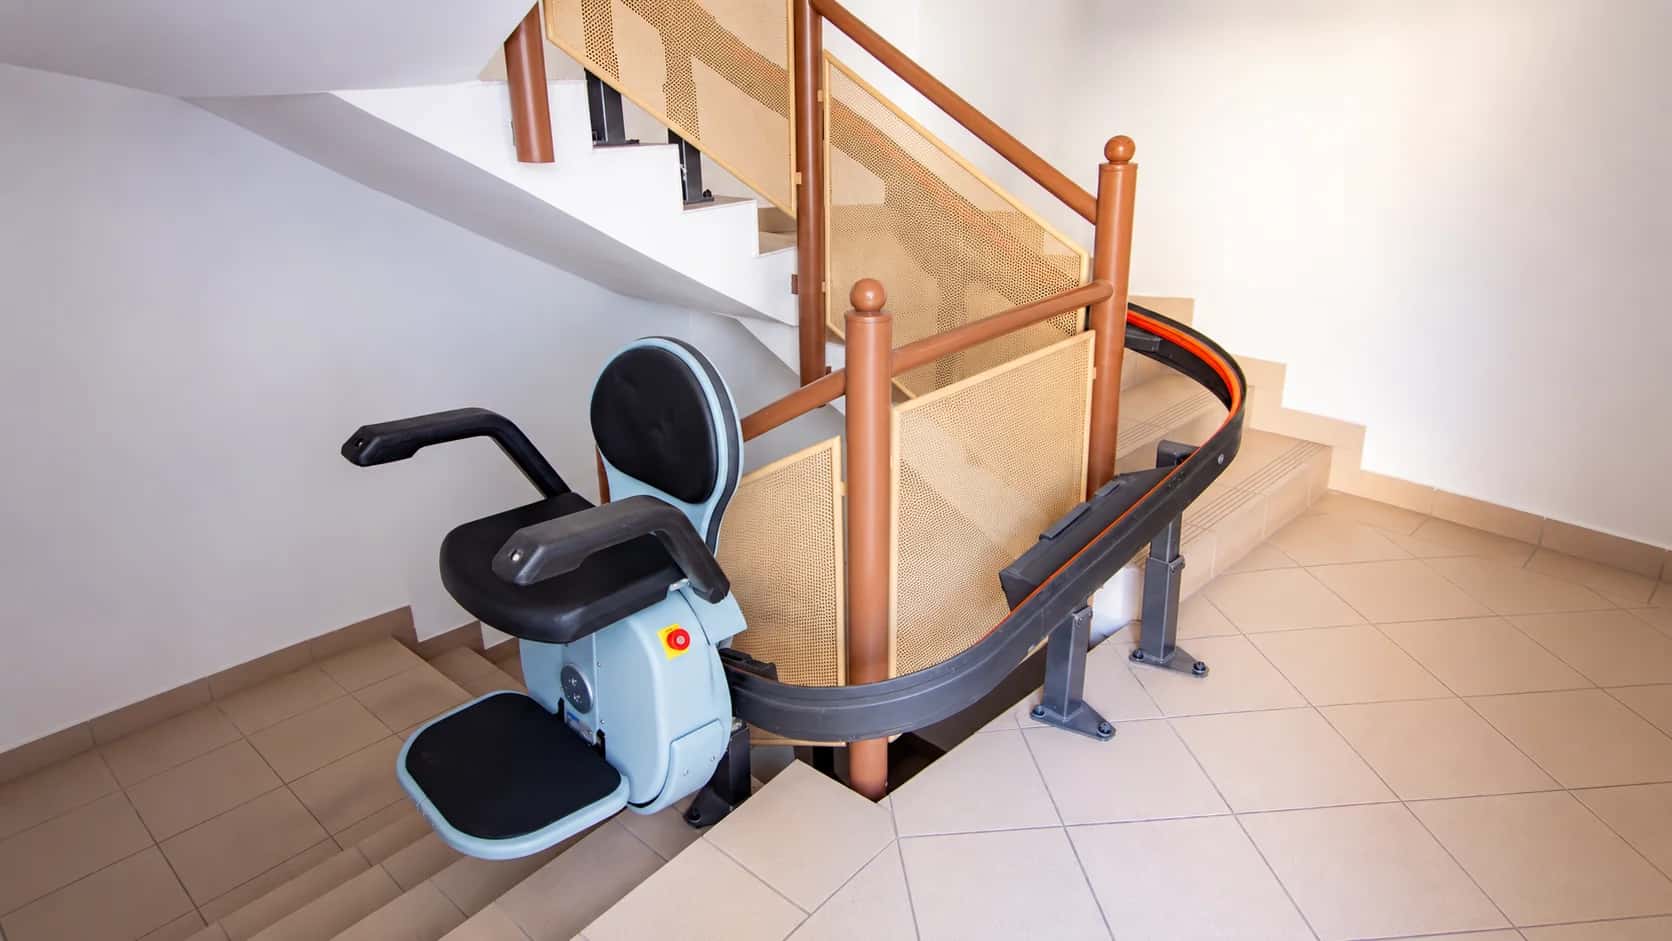
Property that can be used independently of the renovation. This is the broadest exclusion and the one that catches furniture, lift chairs, adjustable beds, walkers, shower chairs and other freestanding equipment. Attachment alone does not rescue an item. In the 2023 interpretation, CRA concluded that therapy equipment mounted to a basement wall was still property usable independently of the renovation.
Household appliances and electronic home-entertainment devices. Excluded by name, including appliances selected for accessible controls or reach.
Voice assistants, plug-in sensors and similar devices fall on the same side of the line, though they can still be useful, as we explain in designing a smart home for aging in place.
Services. Housekeeping, security monitoring, gardening, outdoor maintenance and similar services are out. The split can run through a single purchase: CRA has indicated that a permanently installed wired security system might qualify in the right circumstances, while the ongoing monitoring fees do not.
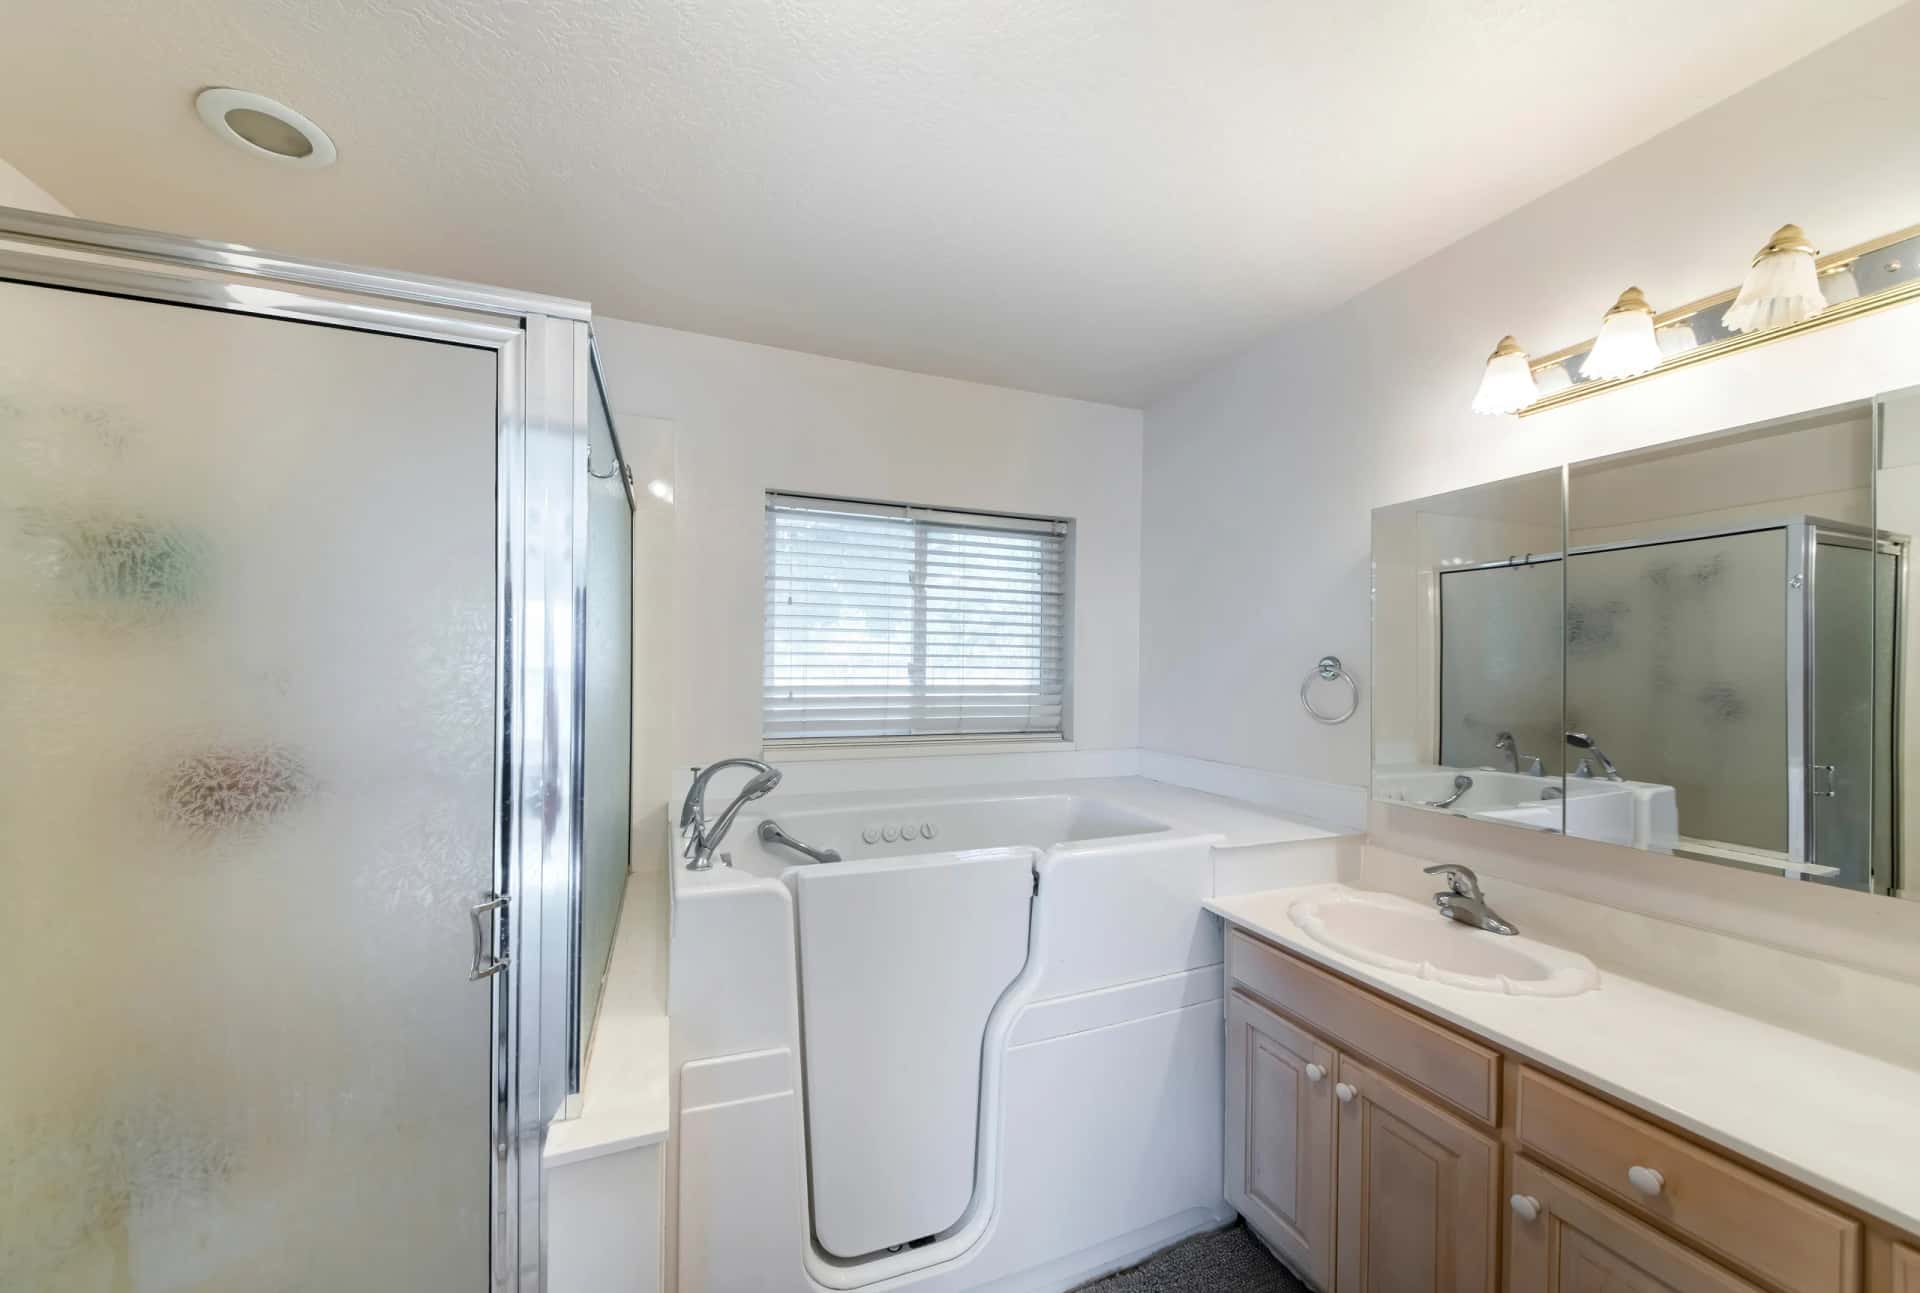
Routine repairs and maintenance. Annual, recurring or routine work is excluded. Re-caulking a shower, servicing a lift and replacing worn stair treads like-for-like are upkeep.
Financing costs, and work done mainly for value. Interest and loan fees are excluded. So is any renovation undertaken primarily to increase or maintain the value of the home, which is the exclusion most likely to be raised against large kitchen and bathroom projects.
Work for income-earning space. An expense incurred to earn business or rental income, such as making a basement suite accessible for a tenant, is not eligible.