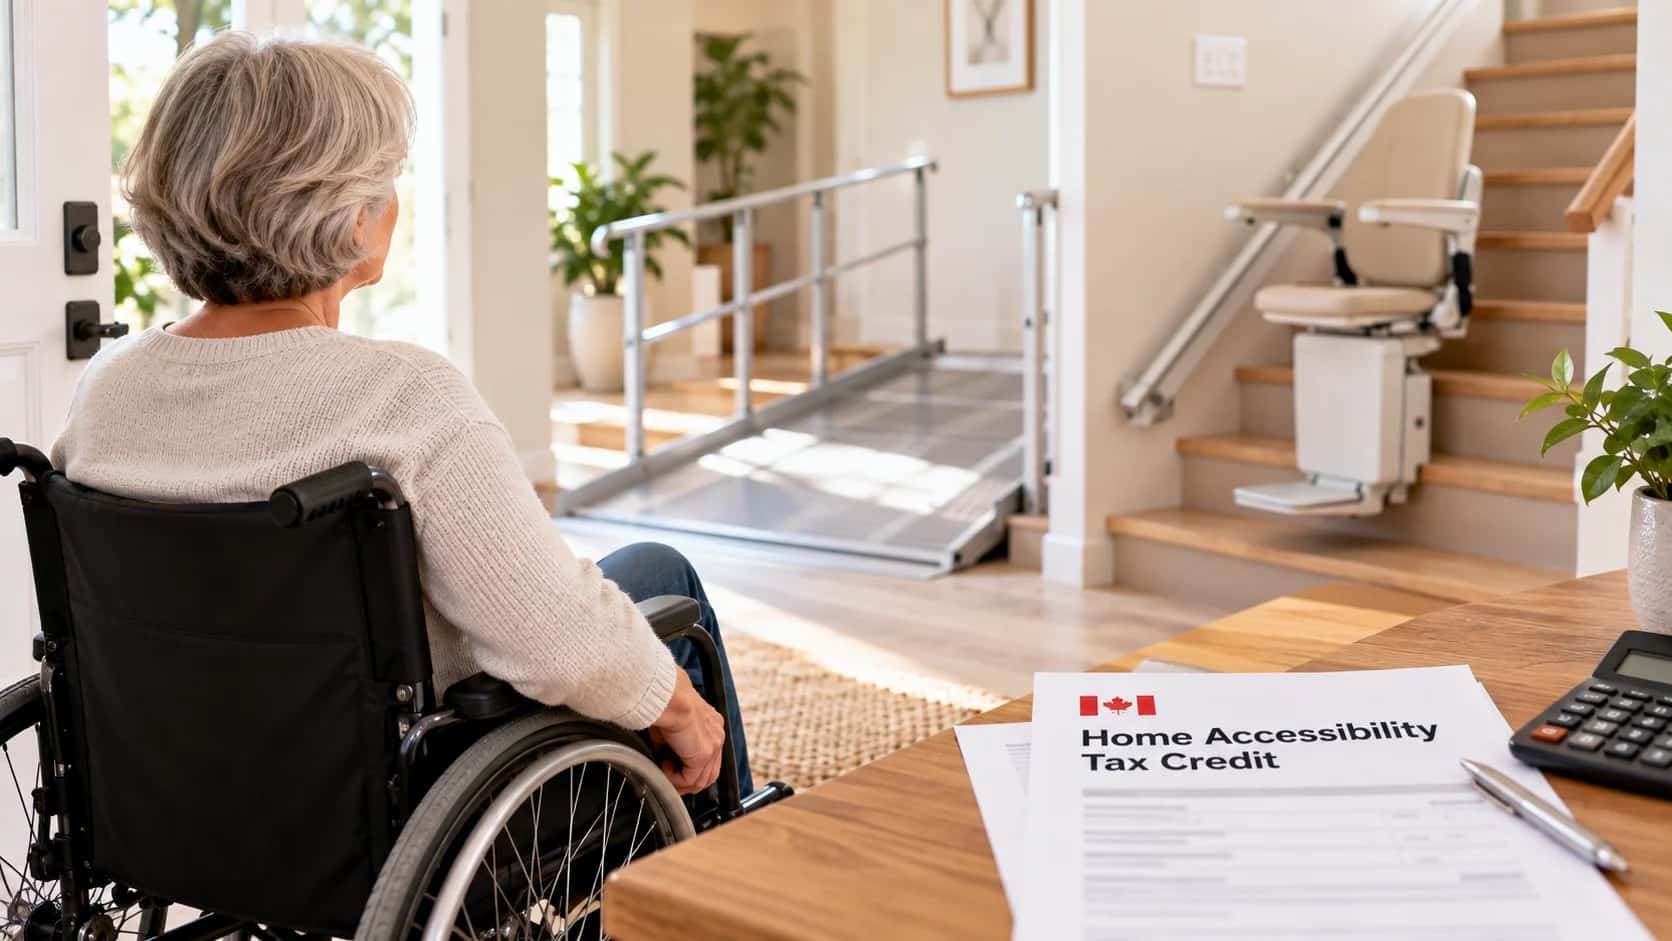
The whole credit turns on one person. The CRA calls that person the qualifying individual, and its line 31285 guidance gives two ways to qualify: being 65 years of age or older at the end of the year, or being eligible for the disability tax credit at any time in the year.
The age test
The age test is measured on December 31 of the tax year. A person who turns 65 in March qualifies for that whole year. So does a person who turns 65 in December, including for work completed the previous spring. A person who turns 65 the following January does not, no matter how close the dates are. Nothing else is tested. Income, health and mobility are irrelevant to the age route.
The Act also covers one hard case. If a person dies during the year and would have reached 65 by year end, they are treated as having been 65 from the start of that year, so expenses incurred before the death are not lost on a technicality.
The disability tax credit test
The second route has no age floor. It asks whether the person is eligible for the disability tax credit (DTC) at some point in the year. Two details matter. Eligibility at any time in the year is enough, so approval partway through the year covers that year. And the test is eligibility, not whether the DTC amount was actually used on anyone's return.
DTC eligibility is a status held with the CRA: a person with a severe and prolonged impairment applies, and the CRA approves the application. A diagnosis, a mobility aid or a provincial disability benefit does not establish it. A person under 65 who has not been approved for the DTC for the year in question is not a qualifying individual, however clear the need for the renovation.
Who else can make the claim
The qualifying individual does not have to be the one who files the claim. An eligible individual can claim for them. That group is narrower than "family":
- A spouse or common-law partner of the qualifying individual.
- A supporting relative, meaning a parent, grandparent, child, grandchild, brother, sister, aunt, uncle, nephew or niece of the qualifying individual or of their spouse or partner, who claimed, or could have claimed, certain dependant or caregiver amounts for that person.
- A person entitled to claim the disability amount for the qualifying individual, where the relative category does not apply.
The claim can be divided between the qualifying individual and eligible individuals. How to divide it is a planning question outside this guide. The rule to hold on to is that splitting never enlarges the limit.
Families planning ahead for a parent often start with technology before construction. Our guide to designing a smart home for aging in place covers that side, most of which sits outside this credit for reasons the next chapter explains.